Showing posts with label Mortgage Arrears. Show all posts

Wednesday, December 20, 2023

The Ongoing Trickle of Repossessions

The latest mortgage arrears statistics from the Central Bank provide an update for the end of September (Q3) 2023. They show there continues to be a trickle of repossessions.

PDH Repossessions to Q3 2023 - AREA

During the third quarter of 2023, there were ten court-ordered repossessions and ten abandonments/voluntary surrenders of primary dwelling houses.  During 2023, court-ordered repossessions have been occurring at a rate of around one per week.

We are now also provided with a more complete breakdown of repossession activity.  The number of repossessions shown above can be broken down into those carried out by banks and non-banks. Non-banks include regulated lenders such as Pepper and Start and also unregulated loan owners.  The chart below shows a split out of the maroon area in the opening chart.

PDH Repossessions by Banks and Non Banks to Q3 2023

In the last 15 years, there has been a total of 3,400 court-ordered PDH repossessions. Of these around 70 per cent have been undertaken for banks. However, the banks stalled their execution of repossession orders in early 2020 (likely pandemic related) and there has been no increase since.  In the year to the end of September, there were 57 court-ordered repossessions and 42 (nearly 75 per cent) were carried out for non-banks.

Figures on legal proceedings suggest that the banks have pretty much ceased using legal proceedings to obtain repossessions orders.  Here is the number of accounts with legal proceedings in progress.

PDH Legal Proceedings by Banks and Non Banks to Q3 2023

In early 2016, the banks had almost 12,000 PDH mortgage accounts with legal proceedings in progress. The last figures show that this had fallen to just 1,100 by the end of September. This is 0.2 per cent (1 in 500) of the 594,000 PDH mortgage accounts held by the banks.

Some of the reduction, of course, came about as the non-performing loans were sold to non-bank entities but the fall in the overall total is very clear. And it can be seen that the level of non-banks has been stable in recent years. In Q1 2019, non-banks had 4,400 PDH accounts with ongoing legal proceedings. The latest figure for these entities is 4,300.

That is not to say there has been an improvement in the mortgage accounts held by non-banks.  The arrears on these accounts is still very high.

PDH Mortgage Accounts with Non Bank Entities Q3 2023

Of the 710,000 or so PDH mortgage accounts in the latest update, almost 115,000 (16 per cent) were held  by non-bank entities.  And of those almost a quarter (27,300) were in some form of arrears.

The arrears ranged from relatively small (less than 90 days arrears) to incredibly large (over 10 years arrears).  It is bizarre that we have to produce figures for such significant arrears.  Non-bank entities had 21,000 PDH mortgage accounts that were more than 90 days in arrears.

Included in that are 4,500 accounts that are more than ten years in arrears.  The total balance outstanding on these loans is €1.3 billion, giving an average balance of €280,000.  There have been €833 million of missed payments on these giving an average level of arrears of just under €185,000.   That is an incredible amount of missing payments.

It is worth noting again that arrears is not a good measure of current loan distress. It does not tell us when the payments were missed.  An account that had two years of missed payments a decade ago but has had every payment made since will be counted as being two years in arrears.

Also, the measurement of arrears in terms of days past due is impacted by the repayment required.  If an account has had €6,000 of historical missed payments and the required monthly payment is €1,000 then that account will be 180 days (six months) in arrears.  If the required monthly payment rises to €1,200 – due to. say, interest rate increases – and there is no new arrears, then the €6,000 of historical arrears becomes the equivalent of 150 days (five months) of arrears. 

This measurement issue won’t impact a count of the total number of accounts in arrears.  There has been no rise in the total number of accounts in arrears.

PDH Mortgage Accounts in Arrears Q3 2023

As shown above, there remains around 29,000 PDH mortgage accounts which are more than 90 days in arrears.  Of these 21,000 are held by non-bank entities.  The banks have 8,000 such accounts but this represents just 1.3 per cent of the total PDH mortgages they hold (594,000).  The banks do not have a problem with a long-term mortgage arrears.

In some cases this will have occurred with the borrower getting back in track either with or without a cure or modification. In other cases it is because the banks have simply sold the loans.  There were plenty of claims that these sales would lead to a surge in repossessions. All we have seen so far is a trickle.

Tuesday, February 20, 2018

PDH mortgages held by unregulated loan owners

Unregulated loan owners have been buying distressed mortgage loans over the past number of years.  Some figures on the numbers and arrears position of mortgage accounts held by non-bank entities (regulated non-bank retail credit firms and unregulated loan owners) have been included in the Central Bank’s mortgage arrears statistics since the end of 2013 and the level of detail provided has improved periodically since then. 

The regulated non-bank retail credit firms includes entities such as Dilosk, Haven, Pepper, Springboard, Start and Stepstone.  The unregulated loan owners are the “vultures”.

Initially, aggregate figures for all non-bank lenders that combined primary dwelling house (PDH) and buy-to-let (BTL) mortgages were provided.  At the start of 2016, separate figures for PDH and BTL accounts were provided and from the second quarter of 2016 these were further broken down by non-bank retail credit firms and unregulated loan owners. 

The table shows the progression of the breakdowns provided and the detail focuses on those PDH mortgages held by unregulated loan owners.

Mortgage Accounts with Non Bank Lenders

We can see that the total number of mortgages (PDH + BTL) held by non-bank entities rose sharply during early 2014. The number reached 47,000 by the end of the year and has stayed pretty close to that level ever since.

The number of PDH accounts held by non-bank lenders was first provided at the start of 2016 and the figure has remained close to the initial value of 38,000.  From Q2 2016 we have been told the number of PDH accounts held by unregulated loan owners.

This started off at just over 10,000 and the number peaked at just over 12,200 at the end of 2016 and had fallen to 11,300 by the third quarter of 2017, with the total outstanding balance tracking moving from €1.9 billion to €2.4 billion to €2.2 billion over the same period. 

The reason for the recent decline is not provided and it could be, in part, a reclassification issue as the total number of loans (PDH plus BTL) held unregulated loan owners was largely unchanged over the period. The total was 18,200 in Q4 2016 and was 18,100 in Q3 2017. 

At the end of Q3 2017, the average balance on the PDH mortgage accounts held by unregulated loan owners was €190,000.  As it is possible for more than one account to be linked to the same PDH property it is likely that the 11,300 accounts corresponds to around 9,000 properties.

And here are the details of those accounts which are 720 days or more in arrears.

PDH Mortgage Accounts Arrears with Unregulated Loan Owners

Over 40 per cent of the PDH mortgage accounts held by unregulated loan owners are more than two years in arrears and these accounts make out almost 60 per cent of the total balance due on PDH mortgages to these entities.

The average balance on the accounts more than two years in arrears is over €250,000.  The figures giving the amount do not seem that reliable with a near 50 per cent jump showing for Q1 2017, so there is possibly some measurement or reclassification issue at play.  Taken at face value the Q3 2017 would indicate that the average amount of arrears on PDH mortgages which are more than two years in arrears held by unregulated loan owners was almost €130,000. 

That is an extreme level of arrears and seems incredible.  That would be six full years of missed payments on a 20-year €250,000 loan at an interest rate of six per cent.  There may be some instances of that but to suggest it is the average seems unlikely.

We don’t have much insight into the repossession activities for these entities.  In the Q1 2016 release it was shown that in that quarter between PDHs and BTLs unregulated loan owners and non-bank retail credit firms repossessed 15 properties on foot of a court order and took possession of a further 57 properties via a voluntary surrender arrangement.  Those made up about about five per cent of repossessions and 25 per cent of voluntary surrenders in the quarter.  However, without other observations it is difficult to make any meaning of those.

Repossession by Non-Bank Entities Q1 2016

In recent quarters a table like that above has not been provided and we have only been provided with the number of properties in possession of the entities at the end of the quarter rather than their repossession activity.  The number of PDH properties in the possession of unregulated loan owners at the end of the last three quarters were:

  • Q1 2017: 183
  • Q2 2017: 186
  • Q3 2017: 187

Without knowing the underlying repossessions and disposal amounts nothing can be gleaned from these figures.  It would be useful if the table provided in Q1 2016 was made available for PDH accounts held by unregulated loan owners which would show the level of court-ordered repossessions and voluntary surrenders involving these entities.  Getting some insight into the number of forced sales would also be useful and that applies to all mortgage providers not just unregulated loan owners.

What will happen to the loans held by unregulated loan owners?  It is still not clear but if proposed sales go ahead there is a good chance that they will increase.  After such sales are completed we can expect the numbers to decrease but how that will be achieved (redemptions, repossessions or resales) remains to be seen.

Wednesday, June 21, 2017

Where are the vulture funds?

On the 20th of June, the Oireachtas Finance Committee held a meeting on the National Co-Op Housing Bill.  One of the proponents of the Bill is Edmund Honohan, the Master of the High Court.  A report on the meeting is available here.

Let’s just consider one extract:

Mr Honohan also said his “overwhelming impression anecdotally” was that individuals before the courts in relation to these matters were sub-prime borrowers “who should probably never have been given mortgages in the first place”.

Anything that is based on someone’s “overwhelming impression anecdotally” probably doesn’t have much going for it to begin with.  The piece later says:

Mr Honohan said the “flattish level” of repossessions at 150 per quarter until the beginning of 2014 “doubled overnight” to in excess of 300. “I can think of no significant factor which might account for this sudden change other than the sudden arrival of vulture funds into our distressed mortgage mess,” he said.

“If that is so, you must presume that if the banks are now proposing to finally sell off their huge numbers of deeply indebted loans to the private sector, perhaps increasing the non-bank proportion of non-performing housing loans fivefold from less than 10 per cent to over 50 per cent, we can expect a further significant jump in possession cases.”

We’ll come back to this one. But let’s start with the “overwhelming impression anecdotally” that it is borrowers from sub-prime lenders who are before the courts.

We can check the plaintiffs in civil possession cases in the legal diary notices published on the Courts Service website.  Most mortgage repossession cases are listed on the civil lists of the County Registrars in the Circuit Courts. 

As of today (21/06/2017) there are 45 County Registrar lists that contain cases involving mortgage repossession.  These are for various dates in May, June and July and cover all eight circuit court districts and almost all counties within each circuit.  In total, it was possible to identify almost 1,900 repossession cases on the legal diary for County Registrars.  This is not all repossession cases before the courts as cases not listed for a sitting around this time will not be on the legal diary.  There are probably 10,000 to 12,000 mortgage repossession cases ongoing.  So we have maybe one-fifth of them in the sample extracted today.

Here are two pieces of information on these 1,900 cases.  The year represents the year the proceedings were submitted to the court and the plaintiff is the entity taking the case and seeking the possession order.

Circuit Court Repossession Cases

The 1,874 cases are split into lenders and those who have acquired loans, i.e. vulture funds.  These funds make up 15 per cent of the cases in the lists extracted and the year in which these cases were initiated can also be seen.

Let’s consider another group taking repossession cases. Let’s include AIB, BOI, EBS, PTSB, KBS and Ulster Bank and make a bit of a leap that we can exclude them from the class of subprime lenders that the under the “overwhelming impression anecdotally” are bringing repossession matters before the courts.

Well, between them these six lenders have 76 per cent of the cases on the list.  I don’t know what an “overwhelming impression anecdotally” is but in this case it does not appear to be based on evidence.  It seems to be just a wild claim aimed to gather attention.  That it should be coming from the Master of the High Court is alarming. 

Where did I go to find the evidence to refute this wild claim? The Courts Service website.  Is the Master of the High Court familiar with the Legal Diary?  It only took a short while to gather the figures in the above table.  Surely it would be better to rely on evidence rather than an “overwhelming impression anecdotally”?  But the role of evidence in the ongoing mortgage arrears crisis was sidelined a long, long time ago.

Maybe vulture funds will lead to a big jump in mortgage repossessions.  If they want to execute repossessions they will have to get a court order first but so far there hasn’t been a surge of cases from vulture funds on the court lists.  If anything, they seem underrepresented given the proportion of long-term arrears mortgages they hold.  Where are the vulture funds?

At the end of Q1 2017 unregulated loan owners held 5,085 mortgage accounts that were more than two years in arrears.  The average balance on these accounts was €256,300 with average arrears of missed payments of €121,100. 

We have been told that a tsunami of repossessions has been on the way since at least 2010.  To date, there has been no evidence of its appearance and repeatedly warning of its impending arrival does not appear to be costly. 

These warnings have surely added unnecessary stress and worry to already stressed borrowers.  These warnings have been proved wrong time and time again.  Banks may have a issued thousands of proceedings seeking orders for possession but the Irish courts are not bent to granting them.  This is a fact borne out from observation of the process.  But hey, who needs evidence, let’s propose a multi-billion scheme on the basis of one’s “overwhelming impression anecdotally”.

Monday, March 20, 2017

Do we need another category in the mortgage arrears data?

Last week the Central Bank published the Q4 update of their mortgage arrears dataset.  In general the situation is one of steady improvement but are we missing out on some of the underlying trends?

Q4 2016 PDH Arrears

The problem is that an ever larger proportion of the arrears accounts are in the final category for those over 720 days in arrears.  By the end of 2016 there were almost 33,500 PDH mortgage accounts in arrears of more than 720 days.  These accounts had an outstanding balance of €7.5 billion and had accumulated €2.2 billion of arrears.  Here are the reported categories as a proportion of the overall arrears problem.

Q4 2016 PDH Arrears Proportions

At the end of 2016 accounts over 720 days in arrears were 43 per cent of accounts in arrears, 53 per cent of the total outstanding balance in arrears and 89 per cent of the built-up arrears.  Can we really tell what is happening to arrears when so much is reported in an open-ended category?

We can look at what has happened to this category since it was first reported in Q3 2012.

PDH Arrears more than 720 days

There has been some improvement in the number of accounts in this category.  The number peaked in Q2 2015 at just over 38,000 and has now fallen below 33,500.  However both the average balance owing and the average amount of arrears accumulated continue to rise.  There may be a compositional effect at play if it is accounts below the average that are resolved, through whatever means, and removed from the category.

Taking that aside we see that the average balance on these accounts climbs ever higher. For the full period above it rose from €203,400 to €225,800.   This is likely a reflection of no or limited repayments being made to reduce the balance and the accumulated interest being added which increases in the balance.

The average amount of arrears also continues to rise and by the end of 2016 stood at €66,000 for these accounts.  We know these accounts are at least two years in arrears but it is hard to know how deep they go.  If the average monthly payment on these accounts was €1,500 then we are looking at accounts being, on average, something around 44 months in arrears.

It is often argued that very little has been done FOR those who are more than two years in arrears.  But it is also true that little has been done TO them.  It has not been possible to find comparable data for other countries in order to assess the extent to which they have experienced mortgage accounts more than two years in arrears.  Other countries don’t report such figures because it is something which would not be tolerated; some resolution would be applied.  That is not the case in Ireland and cases come before the courts where no payments have been received in five years or even longer.     

When the “more than 720 days” category was introduced in Q3 2012 it contained 15 per cent of accounts in arrears, 17 of the outstanding balance in arrears and 48 per cent of the built-up arrears.  As shown above, those figures are now 43 per cent, 53 per cent and 89 per cent.  OK, part of this reflects the improvements that have seen the arrears figure fall for the past few years but it’s clear these improvements have not been reflected in the 720 day category to the same extent.  A final open-ended category that contains a lot of the observations means we are limited in what can be learned from the data about some of the underlying trends.

It tells a lot about the approach to the problem that it is now necessary to introduce a category for accounts more 1,440 days in arrears.

Friday, March 17, 2017

Arrears is a terrible way of measuring current mortgage distress

The release of the Q4 2016 mortgage arrears statistics generated more interest than has usually been the case for these releases for the past two years or so.  Two elements have featured heavily in the reporting:

  1. That the highest number of PDHs on record were taken into possession by lenders
  2. That there was an increase in “early stage arrears”.

The first of these is fairly easy to identify.  At 455, the total number of PDHs taken into possession in Q4 was indeed the highest on record.

PDHs Possessed

Of these, 112 were the result of a court-ordered repossession while 343 were by agreement between the borrower and lender.  The term ‘voluntary surrender’ is a benign way of putting as the borrower will likely have faced strong pressure from the lender.  Voluntary surrenders are likely in instances where there is negative equity with hopefully agreement also reached on how to deal with any shortfall. 

There will also be instances where the borrowers undertake a forced sale of the property to clear the mortgage.  In these cases the borrowers also lose possession of the property but have some limited control over the process.  Figures for forced sales have never been collected.

The status of the properties taken into possession by the lenders is unknown but a share will be vacant or abandoned properties which should be taken into possession and resold by lenders.

There is also a divergent pattern since the middle of 2015 when there was a 50/50 split between court-ordered repossessions and voluntary surrenders.  Since then the number of court-order repossession has declined with the number of voluntary surrenders going in the opposite direction.

Since this data series began in the middle of 2009, lenders have take possession of 7,100 PDHs.  Of these 4,800 were by way of a voluntary surrenders and 2,300 the result of a court ordered repossession.  This is a small number relative to the scale of the arrears problem.

And it is suggested that part of the arrears problem could be getting worse.  Many reports are the same and this is extracted from one:

The latest arrears figures show that 23,224 mortgage accounts were in arrears for less than three months at the end of last year. This was up slightly on the previous quarter in 2016.

However, it was the first time since September [2012] there had been a rise in the numbers getting into early-stage arrears.

The editors obviously felt this was an important point and used the headline “Spike in mortgage arrears as banks repossess more homes” for the piece.  Here is the Q4 spike:

Less than 90 days in arrears

Hmmm.  There is no spike visible in the chart.  There isn’t even an increase visible.  The spike is an increase of 12.  Total.  In Q3, there were 23,212 PDH mortgage accounts in arrears of 90 days or less; in Q4 the figure was 23,224.  Yes, a rise of 12.

Experts said it was too early to say if there was a trend of arrears rising again.

They could also do with saying that the number of people in 90-days arrears doesn’t necessarily tells us anything about the number of people falling into “early-stage arrears” particular when the overall trend in arrears is down.

Arrears measures missed or partial payments relative to the contracted payment amount.  It tells us nothing about when those payments were missed.  If a borrower has a monthly payment of €1,000 and missed €2,000 worth of payments three years ago they will be 60 days in arrears – yet can have made all contracted payments in three years.

If such a borrower has €4,000 of arrears they will be 120 days in arrears.  If that borrower makes an excess payment of €2,000 they will move to being 60 days in arrears.  And this is why the number of accounts in 90-days in arrears is not necessarily a good guide to the number in “early-stage arrears”.  It can also be influenced by people moving from higher categories into lower ones.

And it can happen for odd reasons.  Consider a borrower on an agreed interest-only of €750 with €3,000 of arrears.  The borrower is 120 days in arrears.  If the interest-only period ends and the borrower moves to a capital+interest payment of €1,500 (which we assume they make) the borrower will now be 60 days in arrears.  The borrower has moved into the lower arrears category because their contracted payment has increased but the amount of arrears has remained unchanged.  Such a scenario is highly unlikely but points to some of quirks that the use of arrears as a measure of distress can result in.

Was there a rise in early-stage arrears at the end of 2016?  We can’t say but I doubt it.  It more likely reflects an improvement in the situation (i.e. lower arrears or restructures moving people into lower categories) than a deterioration.

Tuesday, June 21, 2016

Repossession orders received by the Dublin City Sheriff

Just over a year ago we looked at a presentation given to Dublin City Council on the arrears and repossessions associated with their mortgage loans.  We can now expand this a bit with data from the Dublin City Sherriff on possession orders received and then subsequently executed or withdrawn.  The data is summarised in the following table:

Repossessions Orders Dublin City Sheriff

What do we see?

1 Orders Received From

Over the past five years the Dublin City Sheriff has received 561 possession orders for residential property.  Of these 320 (57 per cent) came from Dublin City Council, 195 (35 per cent) came from banks or building socities, with a small residual classed as “Private” (most of these arise from rental situations and the Residential Tenancies Board).

2 Outcome of Orders Received

The data indicate that around 60 per cent of possession orders are executed (342 out of 544).  The remaining 40 per cent are mainly instances where the situation is settled prior to repossession (possible because the borrower and lender have entered an alternative repayment arrangement) with a small number of instances where the order is withdrawn because they have expired (possession orders usually have a 12- month shelfl life).

Dublin City Council has the lowest execution rate for orders (though does present the most orders).  Around two-thirds of orders presented by banks and building societies are executed with this rising to almost four-fifths for orders listed as “private”.

3 Orders Executed For

In the past five years DCC has had 178 possession orders executed by the Dublin City Sheriff.  This compares to 128 for banks and building societies.  Possession orders sought by DCC will be for a range of situations such as loan delinquincy, rent arrears or anti-social behaviour.  The presentation linked to above states that:

At the end of 2014, a total of 251 accounts are categorised as unsustainable with 154 being assessed for mortgage to rent and the balance of 97 being assessed for possession (there are 25 properties due for repossession in 2015, 12 of which are abandoned).

In terms of DCC repossessions, to date there have been 16 cases of voluntary surrender and 93 District Court repossessions (a total of 109 properties have therefore been taken into DCC’s possession). The vast majority of these (n=100) relate to shared ownership including ‘affordable’ shared ownership. Repossessed properties are located across the city, with the majority in Dublin 10 and Dublin 11.

To date, only TWO households entered homeless services as a result of possession. Both departed to PRS.

So we have 93 loan-related repossessions by DCC up to the end of 2014.  In the four years to the end of 2014 there were 84 repossession orders executed for for banks and building societies in Dublin City.

The presentation also showed that DCC have issued loans to around 2,600 households.  Census 2011 showed that there were 53,000 households in Dublin City who were owner-occupiers with a loan or mortgage.  This suggests that around 50,000 households have loans with bank/building socities/lenders other than DCC.

Thus the 93 repossessions by DCC represenent about 3.5 per cent of the households they have lent to while the repossessions by banks and building socities are about 0.3 per cent of the households they have lent to.  As a percentage of the number of households they have lent to, the repossession rate of DCC is ten times greater than that of banks and building societies.

DCC have around 600 households who are 12 months or more in arrears so the 93 repossessions represents 15 per cent of that figure.  We don’t have regional arrears data for banks and building societies but for the country as a whole 6.3 per cent of accounts are more than 12 months in arrears.  If this holds for mortgaged households in Dublin City then around 3,200 households in Dublin City have mortgage arrears of 12 months or more with repossessions by banks and building societies over the past five years being four per cent of that figure.  Thus as a percentage of households in arrears of more than 12 months, the repossession rate of DCC is around four times greater than that of banks and building societies.

You can look for mentions of local authority repossessions in the report issued last week by the Housing and Homelessness Committee. You won’t find any.  But you will find a recommendation for a moratorium on repossessions. Go figure.

Friday, June 10, 2016

Mortgages with Non-Bank Lenders

A relatively recent feature of our ongoing mortgage crisis has been the focus on “vulture” funds.  Since the end of 2013 the Central Bank have provided some data on mortgage accounts held by “non-bank lenders” and the coverage of this has increased in recent releases.  Some of these entities are probably not “vultures” as  typically used and may be interested in servicing performing loans rather than trying to work through a package of non-performing loans.

First we can look at the number of accounts held by non-bank lenders.  The data go back to the end of 2013 and we can see that there has been little change in the total number of accounts (PDH + BTL) over the past 18 months or so.

Mortgages non-bank lenders

Around 40 per cent of the loans held by these entities are showing arrears of more than 90 days with more than two-thirds of these over 720 days (two years) in arrears.  Non-bank lenders hold 26 per cent of all accounts (PDH+BTL) that are more than two years in arrears and as with the overall number of accounts the number of accounts in arrears as been relatively steady over the past 18 months or so.

These lenders have 9,356 PDH accounts that are more than 720 days in arrears.  The average balance on these accounts is just over €250,000 and the average arrears amount is nearly €70,000.  It is pretty obvious that many of these accounts of three, four or even more years in arrears.

The average balance on the 3,657 BTL accounts held by these lenders with more than 720 days of arrears is €311,000 with an average arrears amount of €111,000 which again indicates that some of the accounts are hugely in arrears.

Today’s data from the Central Bank gave some insight into the restructuring of accounts held by non-bank lenders but it is not clear if the restructures were carried out before the loan was sold by the original lenders.  For what it is worth here are the restructured accounts held by non-bank lenders.

NBL Restructures

These do not seems like substantial restructures given the scale of the arrears apparent in the loan book.  Exactly half of the restructures are “arrears capitalisation” which isn’t much of a restructure at all.  See here.  The next most common restructure is “reduced payment” which may be only temporary in nature.

And the final extra piece of data this quarter relates to the repossession activities of non-bank lenders:

NBL Repossessions

Non-bank lenders repossessed 15 properties on foot of a court order in the first quarter of 2016.  This represents 0.1 per cent of the 13,000 accounts they have that are more than two years in arrears (and as we noted these entities have had these accounts for at least 18 months now).  A further 57 properties were voluntary surrendered or deemed to be abandoned to non-bank lenders during the quarter.  The release does not indicate the number of legal proceedings issued by non-bank lenders which would be a useful addition if the data was to be expanded further. 

As can be seem below there was an increase in the overall number of court proceedings issued in Q1 for PDH properties but we cannot tell where these originated from.

Court Proceedings Issued

Thursday, December 3, 2015

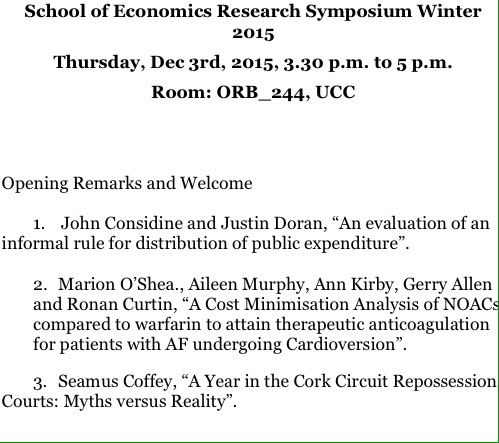
A Year in the Cork Repossession Courts

If you want to know what happens when 892 repossession cases are listed 1,683 times before the Cork County Registrar you might find some answers in this. (pdf, 24 pages)

Mortgage Repossession Hearings before the Cork County Registrar: Myth versus Reality

I will presenting and discussing the findings this afternoon (03/12/15) in UCC with this table probably providing the broadest summary.

Table 14

Wednesday, October 28, 2015

Cork Repossession Hearings in October

There were five hearings before the Cork County Registrar of civil possession cases in October.  Across the five dates some 369 cases were listed and all bar two of these involved residential property (PPRs and BTLs).  The outcomes are summarised below:

October Repossession Hearings in Cork

Compared to earlier sittings there are now more cases being struck out and this happened to 13 per cent of the cases listed in October.  It is not always stated why a case is to be struck out but some of the reasons given are:

  • the property has been sold or voluntarily surrendered and the legal proceedings are unnecessary.
  • the person is back making full repayments on the mortgage
  • there are legal issues that mean the proceedings must be withdrawn (some of these relate to the Finnegan judgement)

The most frequent outcome when cases come before the County Registrar is for them to be adjourned.  In October, 98 cases were adjourned as per the practice direction of the President of the Circuit Court which requires that possession cases involving mortgages be adjourned on their first date before the court.  Even more cases were adjourned by the lenders themselves with 141 cases adjourned by the applicant banks.

There are many reasons for this.  Some are for legal reasons such as to change the name on the civil bill because the loan has been sold but most are because there is on-going engagement with the borrowers.  The banks can seek time to assess a recently submitted SFS or they can seek time to see if the borrower can adhere to a revised repayment amount for a test period.  Some cases are adjourned generally with no new date given but  the applicant has “liberty to re-enter” if circumstances change, such as the borrower not adhering to an long-term repayment arrangement.

There were 48 cases listed which could not proceed because notice of the case had not been served on the borrower.  This seems to be a combination of borrowers who cannot be found (thus substitute service such as ordinary post or pinning the notice to the property is required) and instances where the lender has issued a civil bill but not formally served notice on the borrower (possibly because some engagement is now taking place).

Cases where service cannot be effected will likely conclude with a possession order being granted (with many of these properties likely to be vacant) while cases were service has been delayed will hopefully be struck out at a future return date (if the borrower can resume payments to the satisfaction of the lender).

There were 27 cases where the lenders proceeded with their application for a possession order.  They were granted two possession orders, of which one was by consent.  In the 25 other cases where the lenders sought an order the case was adjourned against their wished.  About half of these were back to future hearings of the County Registrar with the other half sent for hearing before a judge of the Circuit Court.

All the 91 cases that were on the list for the 28th of October are cases that had previously been heard before the County Registrar.  Of these, 18 had been adjourned by the County Registrar in previous sittings where the lenders had sought to proceed with their application for a possession order. 

When these cases came around again in October the lenders sought to proceed in just five of the cases while the other 13 were adjourned by the lenders as engagement, of some level, was now taking place.  One case where the lender had previously sought an order for possession was adjourned generally by the lender with liberty to re-enter.

Of the five cases where the lender proceeded again with their application for possession four were adjourned by the County Registrar and in three of these this was the third time this year this happened.  In one of these no payment had been made since 2009 and the arrears are over €120,000.  A proposal for a lump-sum payment was made at a hearing back in July but has not yet materialised.  The borrower had legal representation in court who said the lump-sum would be available in May 2016.  The case was adjourned to February with the Registrar requesting that some regular payments be made in the interim. 

One order was granted and that was by consent with the borrower present in court.  For notes on this case from a hearing last July see case #10 on this list.  Typically a stay of three to six months is applied to such orders but the borrower asked for a short stay as they were no longer using the property. It was set at one month.

In this hearing there were nine cases where the lenders proceeded for the first time with their application for a possession order.  All of these cases were adjourned.  In five of them the borrower was present or represented in court and got an adjournment very quickly with very little information provided.  There was more discussion of the other four and the details are summarised below (click to enlarge):

Possession Orders Refused 29-10-15

Of the total of 369 cases heard in October about 310 will appear on future lists for sittings of the County Registrar.  And no doubt will accumulate fees for the legals involved.

Thursday, August 6, 2015

Are there 60 home repossession orders being made every week?

Here is part of the front page of The Irish Times today.

Irish Times 06-08-2015

Our attention here is drawn to the story on the right hand side and, in particular the headline.  Are there 60 repossessions orders for homes being made each week?

Hmmm. No.  To be fair the text of the article does not say this even if the figures are presented in a slightly equivocal way.  So lets see what the figures say.  The article says that:

A total of 900 repossession orders were granted in the State’s 26 Circuit Courts between January and June

There were 26 weeks between January and June so this would seem to give a weekly average of 35.  However we are told:

The number of dwellings against which repossession orders were granted averaged 58 per week during the first quarter sittings. This rose to 62 per week in the second quarter.

The 900 repossession orders spread across the 15 weeks that the courts sat for is indeed 60 per week but the headline does not say “courts order 60 repossessions of homes each week they sit”; it just says each week.

The headline makes a reference to “homes” and quote above refers to “dwellings” but possession orders can be granted under one of three headings (with number granted by Circuit Court in first half of 2015 in brackets):

  • principal primary residences (616)
  • buy-to-let residential investment properties (126)
  • other including land, sites, farms and commercial premises (158)

If the focus is just on “dwellings” then the average number of repossession orders granted per sitting week is 50 rather than 60.  For primary homes the equivalent average is 41.

And the 616 orders for primary homes across 26 weeks gives a weekly average of 24 in the first half of 2015 or 29 if including BTLs.

The sittings in Cork get special mention for having the highest number of orders in the country:

The highest number was at Cork Circuit Court, where 123 repossession orders were granted – 91 for primary homes and 32 for buy-to-lets and others.

The figures from the Courts Service show that the there were 91 PPRs, 4 BTL and 28 non-residential properties in the 123 orders granted.

Of the 95 orders granted against residential properties 60 were in the first quarter and 35 were in the second quarter.  Of these 35 order, 30 were granted at sittings of the County Registrar (which I have attended) while five were granted by judges at full sittings of the Circuit Court (I went once – it is a circus).

Here is a summary of the six sittings that saw the 30 orders granted by the County Registrar in Cork in the second quarter.

Repossessions Hearings - Easter Term

More details of the 30 orders granted are below the fold.  It can be seen that around one-quarter of the orders are for BTL properties while around one-third are for properties that are vacant.  These two categories account for nearly 60 per cent of all orders granted in Cork.

If there is an average of 29 possession orders for dwellings being granted across the country each week then it is likely that around 17 of them are for BTL or Vacant properties.  That means we are left with “courts order 12 repossessions of homes each week”.  But that doesn’t make for a good front page headline.

Wednesday, July 29, 2015

Repossession cases adjourned in April coming around again

There are 90 cases listed for hearing on the Cork County Registrar’s Civil Possession list today.  Of the cases listed most of them have been tracked at previously attended sittings back in April and were adjourned to today’s sitting.  Two of the sessions were summarised here. The reasons the cases were adjourned to today’s date are:

  • 5 were adjourned to allow a motion to change the name of applicant be submitted (mostly because the loan was sold to another party).
  • 26 were adjourned because alternative repayment arrangements were either in place or under negotiation.
  • 3 were adjourned because the respondent(s) had not been formally served notice of the legal proceedings in advance of the previous sitting.
  • 39 were adjourned under the practice direction of the circuit court where all legal proceedings involving homes are adjourned on their first appearance in court.
  • 11 of the cases were adjourned even though the bank sought to proceed with the application for the final possession order but had the case adjourned against their wishes.

The outcomes will be updated here later today with the 11 cases where the lenders previously sought final possession orders of particular note.

UPDATE:  Today’s session actually had 97 cases (as opposed to the 90 listed) and was completed in around two hours.

There were issues relating to the formal service of the legal proceedings to the borrowers in the seven cases added and two of the listed cases so these could not proceed.  There were two non-mortgage possession cases on the list so we are left with 86, all of which are in the previous outcomes listed above.

Eight of 86 cases heard were struck out.  It is not always stated why this action is taken.  Sometimes it is because the property has been sold or voluntarily surrendered and the repossession proceedings must end.  In a few cases today proceedings were struck out because of issues of jurisdiction (i.e. the Murphy judgement).  It is rare to hear of a case being struck out because repayments have resumed.  There are many cases where payments are being made and if these are as agreed such cases are usually adjourned to a later date or, in some cases, adjourned generally with liberty to re-enter which is akin to being struck out.

Of the remaining 78 cases the borrowers were absent from the court in 59 cases with the borrower present and/or represented in 19 cases.  The legal representatives of the banks sought adjournments in 58 cases for various reasons while there were 20 cases where they wished to proceed with their application for the final order for possession. Ten possession orders were granted and these are summarised below.

Orders Granted 29-07-15

None of the orders granted were contested.  Three of the cases were where the bank wished to proceed the last time the case was listed but it was adjourned. These included the one case with an order granted where the borrower was present today (#2 above). This borrower consented to the order and argued for the stay to be reduced from three months to one month! 

There were two cases (#3 and #6) where the bank wished to proceed at the last hearing but had the case adjourned in the presence of the borrower.  For today’s hearing these borrowers were absent and the orders were granted.

Four of these cases had previously been adjourned as per the practice direction and three of them were adjourned on request by the lender.  The borrowers were not present on either occasion.

Five of the ten properties with orders granted against them are vacant.  In most of these cases no payments had been received for significant periods – up to five years.  No payments had been made on the mortgages for any of these vacant properties since 2011.

In one of the cases (#5 above) it can be seen that a payment was made as recently as this month and almost €2,600 was paid in 2015 (almost 40 per cent of the amount due).  Even though the arrears are almost €70,000 and equivalent to more than five years of the current monthly payment if the borrower was present in court this order would not have been granted.  A nine month stay was put on the order.

There were 10 other cases where the lenders wished to proceed to the final order for possession but the cases were adjourned.  In five of the cases this was the second occasion observed where the bank wished to proceed and the case was adjourned.  These cases are summarised below. [Click to enlarge]

Proceed-Adjourned Cases 29-07-15

Most of these cases have pretty substantial arrears and some have gone significant periods with no payments.  However, turning up in court and having some recent payments or indicating a capacity to make some repayments will likely result in an adjournment.  It is not clear that #10 above exhibited either of these.  Of course, an adjournment today does not mean there won’t be an order granted at the next sitting.

There were also three cases adjourned from previous sittings where the banks had sought a final order for possession at the last hearing but were looking for an adjournment at today’s sitting citing “resumed payments”, “talks on-going” and “engagement with borrower”.

So the summary of the 95 cases is:

  • 9 couldn’t proceed because service hadn’t been completed
  • 10 orders for possession were granted
  • 8 cases were struck out
  • 58 cases were adjourned by the lenders
  • 10 cases were adjourned by the County Registrar

UPDATE #2: The last hearing before the summer break took place on July 30th. Hearings will recommence in October!  There were 87 cases listed yesterday. The outcomes were:

  • 75 adjournments
    • 63 adjourned by the lenders
    • 12 adjourned by the (visiting) County Registrar
  • 6 cases were struck out
  • 6 orders for possession were granted.

There were 18 cases where the lenders wished to proceed with their application for an order for possession.  These are summarised in the table below.  They are divided between cases where the borrower was absent and cases where the borrower was present and/or represented.

It can be seen that orders were only granted against borrowers who were absent.  All borrowers who were presented or represented in court had their cases adjourned.  There were two cases adjourned where the lenders wished to proceed in spite of the borrower being absent.

Here are the details that were provided to the court. [Click to enlarge]

Cases Proceeded 30-07-2015

Repossession cases adjourned in April coming around again

There are 90 cases listed for hearing on the Cork County Registrar’s Civil Possession list today.  Of the cases listed most of them have been tracked at previously attended sittings back in April and were adjourned to today’s sitting.  Two of the sessions were summarised here. The reasons the cases were adjourned to today’s date are:

  • 5 were adjourned to allow a motion to change the name of applicant be submitted (mostly because the loan was sold to another party).
  • 26 were adjourned because alternative repayment arrangements were either in place or under negotiation.
  • 3 were adjourned because the respondent(s) had not been formally served notice of the legal proceedings in advance of the previous sitting.
  • 39 were adjourned under the practice direction of the circuit court where all legal proceedings involving homes are adjourned on their first appearance in court.
  • 11 of the cases were adjourned even though the bank sought to proceed with the application for the final possession order but had the case adjourned against their wishes.

The outcomes will be updated here later today with the 11 cases where the lenders previously sought final possession orders of particular note.

Wednesday, July 22, 2015

Cork Repossession Hearing - 22nd July 2015

Repossession hearings continued with the County Registrar in Cork today.  This is the 12th session attended and although the overall pattern shows little sign of changing (adjourn, adjourn, adjourn...) some other outcomes were more prevalent in today’s session.

There were 100 cases listed for today with one additional case raised at the end of the list though one of the original cases listed is a discontinued case that should not have been listed.  Thus there were 100 cases and borrowers where either present or represented in court in 43 cases.  There were 57 cases where the borrowers were absent.

Of the 100 cases the initial actions of the lenders were:

  • 65 applications for adjournments
  • 13 cases to be struck out
  • 22 cases seeking the final order for possession

The reasons for the adjournments were mainly because alternative repayment arrangements had been entered into or were being negotiated after the submission of standard financial statements.  Adjournments were also sought in a couple of instances to allow the sale of properties by borrowers to conclude.  In some cases the adjournments were to allow for a change of name of the applicant in cases where loans had been sold.

Of the 100 cases the outcomes were:

  • 80 cases were adjourned
  • 13 cases were struck out
  • 6 possession orders were granted
  • 1 case was held in camera.

It can be seen that possession orders were granted in less than one-third of the instances where the lenders proceeded with the application for the final order for possession (6 out of 21 with the outcome of the other unknown). 

Of the six possession orders granted none were contested.  In two cases the borrowers were present and/or represented and consented to the possession orders while the borrower was absent for the other four orders that were granted.  The details, where provided, are summarised below (click to enlarge).

Possession Orders 22-07-15

Of the 80 cases adjourned most were adjourned to dates in November and December with a few pushed back to February of next year.  There were ten cases which were ‘adjourned generally’.  This means no new date was set but the applicant is at liberty to re-enter at some stage in the future.  Most of these were because alternative repayments arrangements had been entered into and were being adhered to by the borrower.

There were several other cases where the lender sought an adjournment because an alternative repayment arrangement was being entered into.  However when the legal representative of the banks were asked if repayments were being made at present they said such information was not part of their instructions.  It is likely that if repayments were being made that the County Registrar would have adjourned these cases generally rather than to dates in November and December.  Information about current payments would seem to be fairly fundamental to repossession proceedings but it was not available to the court.

Most of the 15 instances where the lenders wished to proceed to the final order but saw the cases adjourned by the County Registrar were because the borrower was present and/or represented in court.  In one such a case a borrower had made no repayments since 2010 and had accumulated arrears of more than €48,000.  The borrower said their circumstances had changed and hoped that things could improve.  The case was adjourned to the 26th of October.

One case was adjourned against the wishes of the lender even though the borrower was not in court to present their circumstances.  This was for a loan with €193,000 outstanding with arrears of €36,000.  The loan first went into default in February 2011.  Various alternative repayments had been entered into in 2010, 2011 (arrears capitalisation), 2012 (interest only) and in February 2014 a reduced payment had been agreed.  Intermittent repayments were made and when reviewing the account statement the County Registrar said that “significant payments” were made in 2014 and that the arrears were “not particularly large”.  The property had previously been sale agreed but the purchaser had withdrawn.  A standard financial statement was submitted when the previous restructuring arrangements were put in place but the lender now deemed the borrower to be ‘non-cooperative’ under the CCMA.  No repayments had been made since January 2015.  The Country Registrar suggested that something may have changed in January of this year given the “significant payments” made in 2014.  The case was adjourned to the 16th of December.

As is usual the cases were heard very quickly and the session lasted just over 90 minutes.

Thursday, May 7, 2015

Presentation to DCC on arrears and repossessions

Last night Dublin City Council were provided with a presentation on some aspects of the home loan schemes run by the council.  There is a lot of interesting material in the presentation and we will focus on just some aspects of it.

Dublin City Council have a loan book with 2,588 accounts (it is one account per household) with a total amount outstanding at the end of 2014 of €309 million, giving an average of just under €120,000 per household.

Of these accounts, 1,192 or 46 per cent were in arrears and these represent €157 million or 51 per cent of accounts by value.  The average balance of the accounts in arrears is €131,000 and the average amount of arrears is €12,677.  Just over half (605) of the 1,192 accounts are in arrears of more than 12 months and these represent for 89 per cent of the arrears amount.

More interesting perhaps are some of the outcomes in relation to sustainability and repossessions.  The presentation states:

At the end of 2014, a total of 251 accounts are categorised as unsustainable with 154 being assessed for mortgage to rent and the balance of 97 being assessed for possession (there are 25 properties due for repossession in 2015, 12 of which are abandoned).

In terms of DCC repossessions, to date there have been 16 cases of voluntary surrender and 93 District Court repossessions (a total of 109 properties have therefore been taken into DCC’s possession). The vast majority of these (n=100) relate to shared ownership including ‘affordable’ shared ownership. Repossessed properties are located across the city, with the majority in Dublin 10 and Dublin 11.

To date, only TWO households entered homeless services as a result of possession. Both departed to PRS.

DCC try to modify loans (mainly using interest-only periods) to reduce the payments for those who engage with them and complete a standard financial statement.  According to the report “the majority of borrowers [in arrears] are working” but around one-quarter are unemployed.

In such cases it may not be possible to make the loan affordable though it is not clear what metric was used to adjudge the 251 accounts as “unsustainable” though a bar of 30 per cent of net income for the payment required under the terms of the loan is used later in the presentation. 

DCC have 90 borrowers who are not paying and not engaging.  These non-payers and non-engagers correspond to 3.5 per cent of borrowers from DCC.

Of the 251 accounts judged to be “unsustainable” the loan agreement will be ended and the property repossessed 97 (nearly 40 per cent) of cases.   The remainder are being assessed for a mortgage to rent scheme.

DCC have already repossessed 109 properties with 85 per cent of these having taken place on foot of a court order.  It is not stated what happened in these 109 cases and whether the household, if any, continue to live in the property under a tenancy agreement.

The presentation highlights that two household contacted DCC’s homeless services following the repossession.  It is not clear why the number was highlighted with the use of capitals.  It could be to highlight that repossessions can result in homelessness though the report does say that both households “departed to the PRS” (presumably private rental sector).  It could also be to highlight that repossession leads to a possibility of homelessness in very few cases – the 109 repossession resulted in ‘just’ two households contacting DCC’s homeless services.

The presentation also indicates that of the 25 properties due for repossession in 2015 that 12 have been abandoned.  In these cases the repossessions will lead to an increase in the supply of housing available and 98FM report that “Houses that have been taken back by the council are given to people who're waiting on the council's social housing list.”

While there can be a threat of homelessness for those who face repossessions it will also be case that repossessions can increase the supply of housing market by bringing back in to use houses that are otherwise vacant and abandoned.

Wednesday, May 6, 2015

Repossession Statistics Distilled

A piece in yesterday’s The Irish Times opens with the following:

The rate at which homes are being repossessed has increased by more than 500 per cent since last year, according to figures from the Courts Service.

Some 586 repossession orders were granted by the circuit court in the first three months of this year, compared with 95 in the same period last year. Of the 586, some 383 were for primary homes, 97 were for buy-to-lets and 106 were “unknown”.

Somewhat confusingly the opening sentence is disputed later in the piece:

A spokesman for the Courts Service said it was important to note that the making of a court order for possession did not necessarily mean that the applicant had obtained possession of the property affected.

“It is a matter for the person or company who obtained the order for possession to pursue its execution. The Courts Service does not have statistics on the number of actual repossessions.”

It is true that the Circuit Courts (mainly through County Registrars) made 586 possession orders in Q1 2015.  However, the 106 that are in the “other/unknown” category refer to commercial property and other assets over which ownership disputes arise.  These should not be included in any analysis of possession orders for residential properties.

Thus in Q1 2015 there were 480 possession orders granted for residential properties (383 primary dwellings houses, PDHs, and 97 buy-to-lets, BTLs).  This compares to 72 possession orders granted for residential properties in the first quarter of 2014.  How this 72 were split between PDHs and BTLs is not available as the Courts Service data did not break down the data by PDH and BTL until the final quarter of 2014.  In Q1 2015 there was an annual increase of 430 per cent in the number possession orders for residential property granted by the Circuit Courts. 

The 383 possession orders for PDHs represents around 1.3 per cent of the 30,000 households with arrears of more than two years on their mortgage accounts at the end of 2014.  If all of these cases were to result in a possession order being granted it would take another 20 years for all those in arrears of more than two years to have a possession order granted against them.

It should also be noted that there wasn’t a large step-change increase in the number of orders being granted in Q1 2015.  The increase has been seen in the data from the second quarter of 2014, with increases in every quarter since.Possession Orders Circuit Court

Of course, the Central Bank produce similar data, and some timing differences (when they are reported by the banks) and coverage differences (all courts rather than just the Circuit Court) aside, they tell a very similar story.  A analysis of the Central Bank data on proceedings and repossessions back to 2009 is here.  Here is a chart of court orders granted for PDHs to the end of 2014 from the Central Bank figures.

Court Orders Granted

The one-off increase in Q2 2013 is difficult to explain but is in the Central Bank release:

During the second quarter of 2013, legal proceedings were issued to enforce the debt/security on a PDH mortgage in 270 cases. Court proceedings concluded in 637 cases during the quarter, and in 350 of these cases the Courts granted an order for repossession or sale of the property.

Aside from the Q2 2013 ‘blip’ the increase in orders granted since Q2 2014 is clearly evident, though the Q1 2015 data which will show a further increase based on the courts’ data has yet to be released by the Central Bank.  Unfortunately the Central Bank do not provide the equivalent legal proceedings figures for BTL accounts. 

Of course, the most visible change in the past 18 months has been in the number of court proceedings issued by lenders which is a function of the moratorium from the CCMA and, more importantly, the Dunne judgement.

Court Proceedings Issued

There is significant additional data in the figures produced by the Central Bank including how many possession orders granted are carried through to a court-ordered repossession. 

Both sources confirm that there was a large increase (relative to a small base) in the number of possession orders granted in Q2 2014.  As most orders are granted with a stay, sometimes of up to nine months, there will be lag between the increase in orders granted and actual repossessions.  The Central Bank data shows that there was a jump in the number of court-ordered repossession in Q4 2014 corresponding to the increase six months earlier in court orders granted.  This chart is taken from the previous post.

Repossessions Chart

If we combine the two charts we can get a rough approximation of how the number of possession orders granted translates into court-ordered repossessions.

Orders and Repossessions

The number of court-ordered repossessions is consistently below the number of possession orders granted.  For the entire period the number of court-ordered repossessions is 40 per cent of the number of possession orders granted.  It is not clear how this will be affected when the big jump in the number of orders granted in Q2 2014 feeds through to the repossession numbers when the lag for stays and other delays has elapsed. This can be expected to average nine months or so.

Sunday, April 26, 2015

AIB at the Oireachtas Finance Committee: Discussion on Mortgage Arrears

Last Thursday AIB appeared before the Joint Oireachtas Committee on Finance, Public Expenditure and Reform to discuss an “Overview of the Banking Sector in Ireland”.  The submissions by AIB prior to the meeting were:

A transcript of the meeting is available here.  The meeting was roughly divided between discussions of AIB’s funding costs and interest rates, and in particular its SVR mortgages, and discussions of AIB’s responses to mortgage arrears.  Here are a couple of extracts from statements made by Brendan O’Connor, AIB’s head of the financial solutions group, on the latter.

Mr Brendan O'Connor:  Those with mortgages over 720 days in arrears represent a large cohort. In AIB, 60% of those have made no payment at all, which represents 7,000 accounts. If that is their maximum affordability, it will not be possible for us to restructure the mortgage. Our responsibility is to help the customer exit the property and we will not go after the residual debt if it is not there. We actually can do nothing unless we have that level of engagement.

AIB has around 11,500 mortgage accounts that are more than two years in years. Because of top-up loans, equity releases and the like this corresponds to around 9,000 properties/borrowers. Of these 9,000 around 5,400 made zero repayments in 2014.  It would have useful if the split of these 5,400 non-payers between PDH and BTL properties was provided.  The AIB representatives stated that they had 7,000 accounts on which no payments were being made but there were no questions put to them by the members of the Committee on this issue.

There were numerous questions about the process AIB engages in with borrowers who do engage.  On this Brendan O’Connor said:

Mr Brendan O'Connor: We make our decisions based on affordability. The only criterion we use is how much somebody can pay. Is there enough there to structure a sustainable mortgage solution? We do not go into matters of policy but affordability for the individual in question. There is always an individual set of circumstances in such cases.

If somebody has some level of affordability that allows for a mortgage restructure, we have a product to allow that to happen. Where someone does not have it, we have a process which allows a voluntary sale for loss and will not pursue the residual debt. The only way we can sustain a restructure is if we have the customer’s information, that they are willing to talk to us and willing to make a payment in line with affordability.

The issue of what happens to the residual debt after a voluntary sale is important. A number times AIB seemed to state that if a borrower engages by  providing financial information but that it is not possible to restructure the mortgage to make it sustainable and affordable any shortfall or residual that might remain after a voluntary sale will be written off.

Mr Brendan O'Connor: To the extent that somebody is involved in a voluntary surrender, where he or she has no affordability and no cash-flow such that we cannot construct a sustainable solution that will allow him or her to keep his or her home, we will look at the residual figure. To the extent that there is no affordability we will write an agreement that states the residual amount will be written off.

Mr Brendan O'Connor: The bank has said that where someone cannot afford their mortgage we will not go after them for the residual debt if they sell the property. In effect, that is the outcome we get if a house goes to possession. It makes more sense for the individual, the borrower and the bank to do that consensually and achieve that outcome rather than go through a possession process. However, I would like to find out how many are in this queue that we can restructure, and that is why we try to get the re-engagement.

This seems pretty clear.  When someone cannot afford their mortgage and undertakes a voluntary sale AIB will not pursue a residual that may remain.  Mr O’Connor also said that this is the outcome if “a house goes for possession”.  However, he was not so clear of what happens the residual after a voluntary sale in this statement:

Mr Brendan O'Connor: Regarding voluntary assisted sales, where someone has no affordability post the sale of the property, we do not go after people for the residual debt. There is not much point. However, we do look at residual debt on the basis of affordability, so to the extent that someone can afford to make some payment to the residual, within those reasonable living expense guidelines etc., we will seek it, and typically a payment for a period that is less than the insolvency period.

Although this is unclear AIB did write off a significant amount of mortgage debt in 2014 – €461 million – the bulk of which it can be assumed came at the end of voluntary sale processes.  Although a conclusion that results in loss of ownership is bad, in circumstances where the borrower cannot afford the mortgage, it should be accompanied with a write off of any residual that may remain.

AIB’s representatives were questioned on their motives for issuing legal proceedings against a significant number of borrowers.  The reason why a bank issues legal proceedings is that it wants to take possession of the house, however, taking this action does lead to significant re-engagement.

Mr Brendan O'Connor: There are some interesting re-engagement levels. We are actively seeking an adjournment in 50% of cases where there is a court date because we have had re-engagement. At certain stages in the process, we tend to get re-engagement and, certainly after we give the regulatory letters, we get re-engagement of about 50% at every stage.

We actually have 800 people in the court process at the moment who are on a test period, so while they will appear in the legal numbers, they have re-engaged. They are on a test payment period and when that test payment period is over, we would expect them to come out of the legal process.

We have brought 2,000 people back from more than two years in arrears who are no longer in arrears when, previously, they would have been in the legal process. It does drive an intensity of engagement and our observation is that it leads strongly to people coming back to the table.

Brendan O’Connor outlined four stages the banks go through when dealing with non-engaging borrowers in arrears who fail to complete and SFS and indicated that at all stages around 50 per cent of borrowers re-engage.

Mr Brendan O'Connor: The week a borrower goes into arrears, he or she receives a letter informing him or her of being in arrears with a standard financial statement, SFS, which we ask him or her to fill out. That is the process by which we judge affordability. If we get an SFS, we will make an offer to the borrower based on the financial detail that come out of that.

Throughout the entire process, to the extent that the borrower does not follow that up, we send out another letter, known as a Provision 28 letter, which states that we need to keep this moving to the extent that if the borrower does not engage with us, we will have to deem him or her non-co-operating. That is followed by what is called a P29 letter. Approximately 50% of those who get a Provision 28 letter engage then.

A P29 letter states one is non-co-operating. At that stage, approximately 50% of those who are still left in that bucket engage. If a person has not engaged by then, at which point he or she has had a quite significant amount of time, he or she will go into the legal process. Approximately 50% of the borrowers engage before it gets to civil bill stage, and after civil bill stage, as I stated earlier, in approximately 50% of the cases that go to court, we are actively seeking adjournments.
It is all about engagement. We ourselves have various channels in the Irish Mortgage Holders Organisation. To the extent that one engages, one will get an offer.

Thus the stages at which 50 per cent re-engage at each point are:

  1. Letter stating that non-engagement may lead to the borrower being deem as “non-cooperating”
  2. Letter stating that the borrower is now classified as “non-cooperating”
  3. Decision made that the bank will enter the legal process to seek possession of the property
  4. Issuing of civil bill to begin legal proceedings and listing of case for court date.

It is also possible that there may be re-engagement if the legal proceedings conclude with the granted of a possession order by the courts but the extent of that, if any, was not stated. 

AIB have indicated that if they make a decision to go down the legal route with 5,000 borrowers around 2,500 will re-engage and a civil bill will not be issued.  Of the 2,500 borrowers who have a civil bill issued to them and have their case listed in court around 1,250 will reengage at that stage and AIB will seek to adjourn the legal proceedings.  Thus of the 5,000 borrowers where the bank decides to go down the legal route the bank will go to court to pursue the order for possession in around 1,250 instances.  It will be a decision of the court whether the orders for possession will be granted.

Finally, Brendan O’Connor stated the circumstances that lead to the bank’s decision to pursue the legal route:

Mr Brendan O'Connor: The other issue that was raised was the tsunami of repossessions. That was misrepresented in the media today. For anybody to be in the position where we are in a court repossession discussion or in the court process would require them to not have engaged or repaid us anything in a number of years. In those cases, significant numbers will not end up in repossession territory at all because I think we have about 50% who re-engage.

Printfriendly